Why So Many Travelers Still Miss This Chase Sapphire Preferred Benefit
- Quick Tags: Chase Sapphire Preferred, Travel Insurance Credit Card, Trip Delay Reimbursement, Credit Card Travel Benefits
- Editor: Maya Patel
- Updated: Jul,25,2026
- Views: 353.7k
Booking a trip usually starts with comparing airfare.
E.g. :The Secret Grocery Cash Back Perk Hidden Inside Blue Cash Preferred
Very few people spend the same amount of time asking what happens if that trip falls apart.
That surprised me after hearing several friends complain about delayed flights, unexpected hotel stays, and missed connections. Many had travel credit cards. Few had ever looked at the protections that came with them.
One card kept coming up during those conversations: the Chase Sapphire Preferred Card. Most people know it for earning travel rewards. Far fewer realize that its built-in travel protections can sometimes become the feature that matters most.
Reward points are easy to compare.
Travel protections are not.
The Chase Sapphire Preferred Card includes several travel-related protections when eligible travel is purchased with the card and the terms are met. These benefits are administered according to the Guide to Benefits and have become one of the card's biggest long-term advantages.
That's easy to overlook because nothing exciting happens when everything goes as planned.
The value only becomes obvious when something doesn't.
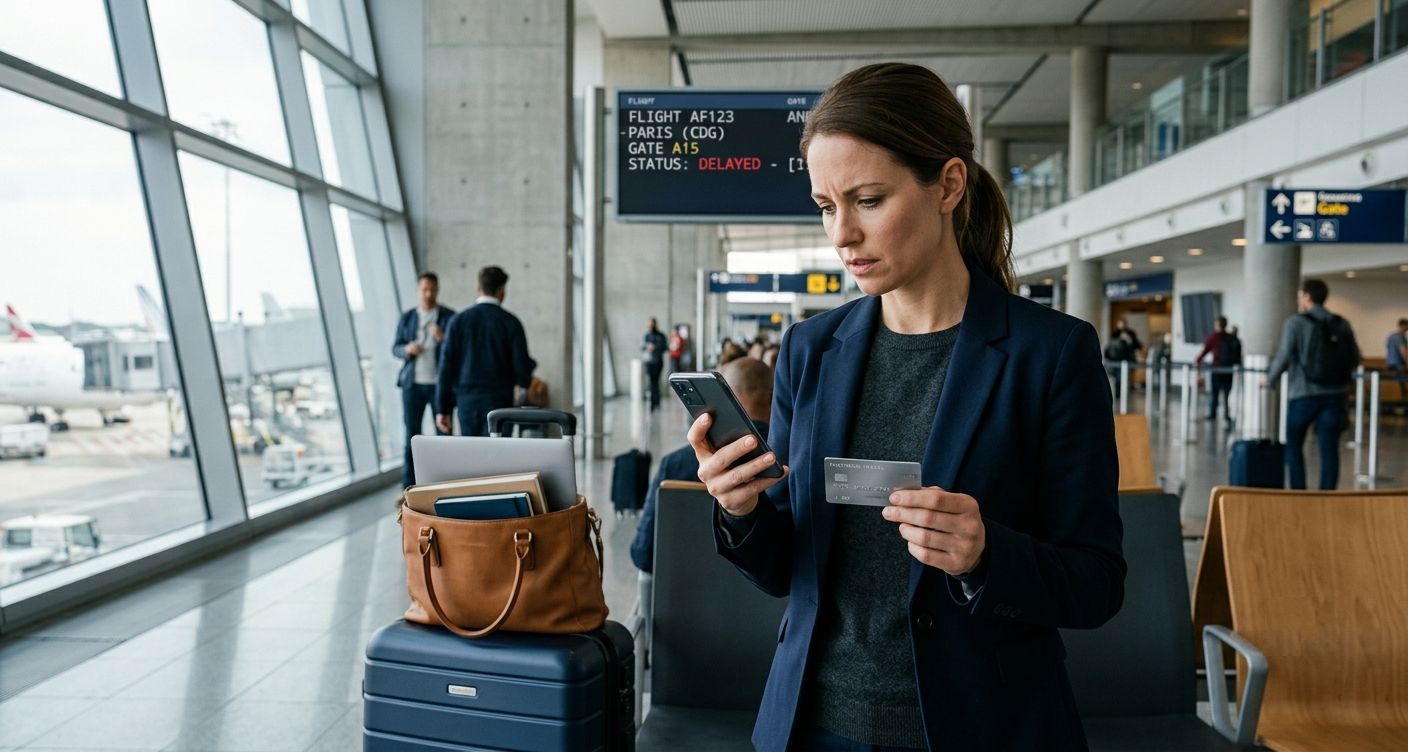
Anyone who travels regularly knows delays are part of the experience.
A late flight may lead to an unexpected hotel stay, meals at the airport, or transportation costs you never planned for.
Many travelers assume every expense automatically comes out of their own pocket.
That's not always the case if your credit card includes eligible travel protections and your trip qualifies under the card's benefit terms.
Understanding those rules before traveling is far more useful than discovering them afterward.
Reward programs receive all the attention.
Insurance benefits usually stay buried inside the Guide to Benefits that few people ever open.
I made the same mistake years ago.
Like many cardholders, I looked at earning points and ignored everything else. Only later did I realize that some of the card's most valuable features never appear in advertisements because they're designed for situations nobody hopes to experience.
Travel interruptions.
Lost baggage.
Rental car coverage.
They're not exciting topics, but they're exactly the kind of benefits that can reduce financial stress during an already frustrating trip.
One simple habit has saved me time more than once.
Whenever I receive a new travel card, I download the Guide to Benefits and spend fifteen minutes reading the travel protection section.
Not every situation is covered.
Coverage limits, eligibility requirements, exclusions, and claim procedures all matter.
Knowing those details before departure makes filing a claim much easier if something unexpected happens.
Travel delays are no longer rare.
Weather, airline scheduling issues, maintenance problems, and airport congestion affect millions of passengers every year.
That doesn't mean every delay qualifies for reimbursement.
Eligibility depends on the card's benefit terms, how the trip was purchased, the length of the delay, and other conditions described by the benefit administrator.
Still, understanding that this protection exists changes how many people evaluate a travel rewards card.
Instead of asking only, "How many points will I earn?"
It becomes, "What happens if my trip goes wrong?"
That question is often worth much more.
This isn't the perfect travel card for everyone.
Someone who flies only once every few years may care more about annual fees than travel protections.
Frequent travelers often think differently.
If you regularly book flights, hotels, rental cars, or weekend getaways, protections built into a travel credit card can become part of your overall travel strategy rather than an afterthought.
The key is not assuming every benefit applies automatically.
Always check the current Guide to Benefits before relying on any coverage.
People who tend to get the most value include:
Travelers who book several trips each year.
Families planning vacations with multiple flight connections.
Business travelers with unpredictable schedules.
Anyone who prefers having extra protection without purchasing separate coverage for every trip.
Not everyone will ever file a claim.
But knowing the protection is available can make travel feel a little less uncertain.
The next time you compare travel credit cards, try asking one extra question.
If your flight never goes as planned, which card would you rather already have in your wallet?